HOA Estoppel Statement: A Complete Guide
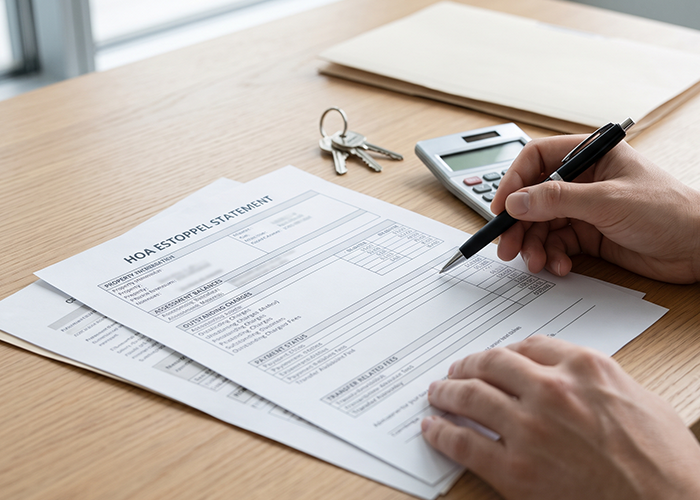
The document may look like a simple form, but accuracy matters. A missed charge or open violation can create confusion at closing, so homeowners and associations should understand what the statement says and how to review it.
Browse By Category
Sign up for Our Newsletter
Sign up for Our Newsletter
Trending Now
The document may look like a simple form, but accuracy matters. A missed charge or open violation can create confusion at closing, so homeowners and associations should understand what the statement says and how to review it.
What Is an HOA Estoppel Statement?
An HOA estoppel statement is a document that reports an owner’s financial and other obligations to a homeowners association as of a stated date. It is often requested during a sale or refinance so the people handling the transaction can confirm what the association’s records show.
The statement may also be called an:
- Estoppel certificate
- Resale certificate
- Demand statement
- Closing letter
These terms do not always mean the same thing in every state. A resale package, for example, may contain governing documents and financial records, while the estoppel statement focuses on the property’s account and transfer details.
The word “estoppel” points to the document’s reliance function. In some states, a buyer or other party who relies in good faith on the certificate may receive legal protection if the association later identifies an amount that the certificate did not disclose.
The details depend on state law, so the document should be prepared and reviewed with local requirements in mind.
Why Is an Estoppel Statement Used?
A home sale involves more than the purchase price and mortgage payoff. The property may carry unpaid assessments, a special assessment, a transfer charge, or another obligation that must be addressed before ownership changes hands.
An estoppel statement gives the closing team a clear account summary. It can help the parties decide which charges need to be paid at closing, which obligations continue after the sale, and whether the association has any approval steps for the transfer.
The statement also creates a record of what the association reported on a particular date. That record can help prevent misunderstandings between the seller, buyer, title company, and HOA after closing.
What Information Does the Statement Include?
The required information depends on state law and the association’s governing documents. Many statements include details such as:
- The property address, parcel or unit number, and current owner’s name.
- The regular assessment amount, payment frequency, and date through which the account is paid.
- Unpaid assessments, late charges, interest, collection costs, or other money owed.
- Special assessments already approved or scheduled to come due.
- Transfer, resale, capital contribution, or other fees tied to the transaction.
- Open violations that the association has formally noticed to the owner.
- Any required approval, right of first refusal, or transfer process.
- The statement’s issue date, expiration or effective period, and the association representative’s signature.
Some states require a set form or specific disclosures. Other states rely on a resale certificate statute or the association’s governing documents. The association should not assume that a form used in one state will meet the rules in another.
When Should a Homeowner Request One?
Most sellers request an estoppel statement after accepting an offer and before the scheduled closing. The title company, closing agent, attorney, or real estate professional may submit the request for the seller. In some places, a buyer, lender, or authorized agent can request it directly.
It is wise to start early. Even when a state sets a deadline, the certificate may take time to prepare, correct, or update. A delay can hold up closing, especially if the association must confirm payments, search violation records, or verify a special assessment.
A homeowner planning to refinance may also need an estoppel statement. The lender or its agent may ask for the association’s current account information to understand whether assessments are paid and whether other charges affect the property.
How the Process Usually Works
The requestor submits the association’s required form or online request, identifies the property, and provides contact details for delivery. The association or its management company then checks the owner ledger, assessment schedule, violation history, and transfer requirements.
The preparer calculates amounts through the date required by the form or statute. If the governing documents or state law permit fees, the association may invoice the requester or another party named in the request. The completed statement is delivered through the allowed method.
Before closing, the title or closing team compares the statement against the transaction figures. If the closing date moves or the certificate expires, the parties may need an updated statement. The buyer and seller should confirm who will request any update and whether another fee applies.
Fees, Deadlines, and Validity Periods
Estoppel fees and response deadlines are not uniform across the United States. State statutes may cap fees, set a standard or expedited deadline, or require the association to waive a fee if it misses the delivery deadline. Governing documents and written management agreements may also affect who prepares the certificate and what the association may charge.
Florida provides one example. For a homeowners’ association governed by Chapter 720, Florida law generally requires the association to issue a requested estoppel certificate within 10 business days. The statute sets fee limits and expedited delivery rules, and it gives an electronically delivered or hand-delivered certificate a 30-day effective period. A certificate sent by regular mail has a 35-day effective period. Florida condominium associations are addressed separately under Chapter 718.
These Florida figures are examples, not nationwide rules. Boards should check the current law for their state and association type before setting a fee schedule or service timeline. Owners and closing professionals should confirm whether the certificate remains valid through the planned closing date.
How State Requirements Can Change the Process
A certificate that works for one community may not satisfy another state’s rules. Some states call the document an estoppel certificate, while others use resale certificate or subdivision information. The required details can also reach beyond the owner’s balance to include association finances, insurance, pending lawsuits, or known property conditions.
Texas offers a useful example of a broader resale disclosure. Under Texas Property Code Section 207.003, the association generally has 10 business days to deliver requested subdivision information, including governing documents and a resale certificate.
The statute lists information that can include regular and special assessments, unpaid amounts, reserves, the operating budget and balance sheet, judgments, lawsuits, insurance, known violations, and transfer fees. It also sets limits on certain preparation and update fees.
That is different in scope from the Florida HOA certificate described above. The point is not to treat one state’s process as a model for every community. Instead, the association should identify which statute applies, whether the property belongs to an HOA or condominium association, and what the association’s declaration and rules require.
A closing professional can help identify which records the parties need, but the association remains responsible for following the requirements that apply to it. When a request seems unusual, confirm the requestor’s authority and required delivery method before sending account information. This protects owner privacy and keeps the timeline clear.
Who Pays for the Estoppel Fee?
The answer can depend on state law, the purchase contract, and the parties’ agreement. In some transactions, the seller pays because the request relates to the seller’s account. In others, the buyer or title company pays upfront, and the closing statement assigns the cost to a party later.
The association should follow its governing documents, adopt fee resolutions, management contract, and applicable law. If the law requires the association to refund a fee when a sale does not close, the association should track the request and closing date so it can process the refund correctly.
A fee should be disclosed before the request is completed whenever possible. Clear information helps the parties avoid a last-minute dispute over a charge that may be due before the certificate is released.
What Should Buyers and Sellers Review?
Read the certificate carefully as soon as it arrives. Check the owner name, property address, account balance, payment dates, fee amounts, and any notes about violations or approval requirements. If something looks wrong, contact the association or manager promptly and provide records that support the correction.
A practical review may include these steps:
- Compare the assessment amount and payment status with recent HOA statements or receipts.
- Ask how each listed balance was calculated, including late fees, interest, or collection costs.
- Confirm whether a special assessment has been approved, is due, or is scheduled to begin.
- Review any reported violation and ask whether it is open, corrected, or under appeal.
- Check transfer fees, application requirements, and any board approval or right-of-first-refusal process.
- Confirm the certificate’s effective period covers the planned closing date.
- Send any correction request in writing and keep the response with the closing records.
The certificate is a snapshot, not a substitute for reviewing the association’s rules and financial health. Buyers who need broader information may also request the resale package, governing documents, budget, meeting minutes, insurance details, or other records available under state law.
How HOA Boards Can Prepare Accurate Statements
Boards do not need to handle every request themselves, but they should make sure the process has a clear owner. The association can designate a manager or other authorized representative, keep the contact information current, and explain where requestors should submit documents.
Good records make a real difference. Associations should reconcile owner ledgers, post payments promptly, track approved assessments, and keep violation notices in an organized file. A consistent review checklist helps the preparer catch missing dates, fees, and signatures before the certificate goes out.
Boards should also review the association’s fee authority and timelines. If the state requires a written resolution or a specific form, the association should keep it with its records. Management agreements should state who prepares certificates, who receives fees, and how urgent requests or corrections are handled.
Digital request portals can help by recording submission dates, storing documents, and showing request status. Still, automation does not replace review. A staff member should verify account details and send sensitive information only to the verified requester or authorized recipient.
Estoppel Statement vs. Resale Package
An estoppel statement usually focuses on a specific property’s account balance and transfer details. A resale package may include a wider set of materials, such as:
- The declaration
- Bylaws
- Rules
- Budget
- Financial statements
- Insurance information
- Meeting records
- Required buyer disclosures
A buyer may need both. The estoppel statement can clarify what is owed at closing, while the resale package helps the buyer understand the community’s rules, finances, and day-to-day expectations. Since terminology varies, ask the association or closing professional what each request includes.
What If the Statement Is Wrong or Out of Date?
Raise the issue with the association in writing as soon as possible. Point to the exact line, explain why it appears incorrect, and include:
- Receipts
- Account statements
- Other supporting documents
Ask for a corrected or amended certificate and confirm whether the correction changes the effective period.
Do not assume that a phone conversation changes the written certificate. Request confirmation of any corrected amount or status in writing and share it with the title or closing team. If the parties cannot resolve a major discrepancy, they may need advice from a real estate attorney familiar with the state’s HOA laws.
If the closing date changes, check the expiration date rather than relying on a certificate that was accurate when first issued. Request an update when the document no longer covers the transaction date or when new charges may have posted.
Clear Records, Smoother Closings
An HOA estoppel statement gives the closing team a useful account snapshot, but its value depends on accurate records and timely review.
Homeowners should request it early, buyers should check it closely, and associations should follow the law and their own written procedures.
A smoother estoppel process starts with organized records and dependable management support.
The right partner can simplify resale coordination, closing procedures, and daily operations. Explore our directory today to get started.
Related Articles:
Trending Now
Related Article
Sign up for Our Monthly Newsletter
Sign up below for monthly updates on all HOA Resource